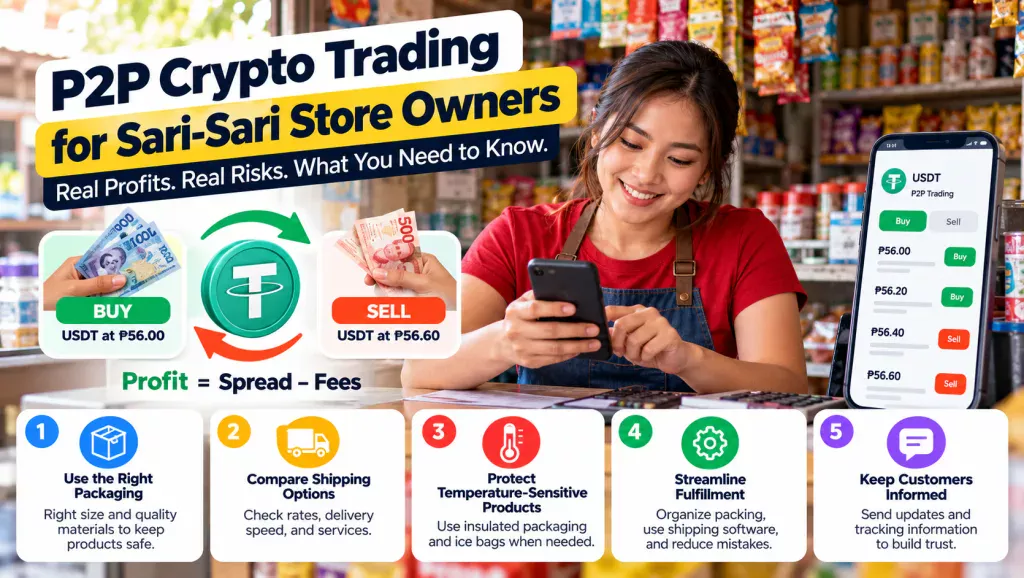
Every sari-sari store owner already understands the core of peer-to-peer crypto trading. You buy stock at one price, sell it at a slightly higher price, and live on the difference after costs.
P2P crypto merchants do the same thing with digital assets, usually stablecoins such as USDT or USDC. The real question for a first-timer is not whether the model works on paper. It is whether the margin survives fees, idle capital and the occasional bad customer.
What a P2P merchant actually does
On a P2P platform, users post offers to buy or sell crypto for local money. A merchant is someone who keeps offers live on both sides: buying from people who want cash and selling to people who want crypto.
The merchant sets the price, the minimum and maximum order size, and the payment methods accepted, such as bank transfer, e-wallets or cash.
What you are really selling is convenience. Customers accept a slightly worse rate in exchange for a quick trade, a payment method they already use, and a counterparty who answers messages.
Where the money comes from: the spread
A merchant’s income is the spread, the gap between the price paid when buying crypto and the price charged when selling it.
Spreads move with competition and demand. In busy markets with many merchants they tend to be thin, because customers simply pick the better offer.
Stablecoins add one more factor. USDT and USDC aim to hold one US dollar, but P2P prices in local currency often sit above or below the official exchange rate, especially where dollars are scarce. That gap, the premium, shifts how much room a merchant has on each side.
The cost lines beginners forget
The spread is revenue, not profit. Before you count anything as earnings, list every cost that touches a trade.
- Platform commission. Most marketplaces charge a fee per trade. Read the published fee table rather than guessing.
- Network or escrow costs. On platforms that lock crypto in an on-chain escrow, opening and closing that escrow costs a blockchain network fee. It varies with network conditions.
- Bank and e-wallet fees. Transfer fees, cash-in and cash-out charges, and transaction caps on your accounts all eat into margin or limit your volume.
- Your time. Every order means checking a payment and chatting with a customer. Give that time a price.
A worked example (illustrative numbers only)
These are made-up round numbers to show the math, not real market rates or any platform’s actual fees.
Say you hold 1,000 USDT as inventory. You buy it from one customer at 56.00 pesos per coin and sell it to another at 56.60 pesos. That round trip earns a gross spread of 600 pesos.
Now subtract costs across both legs: 110 pesos in platform commission, 40 pesos in network costs for escrow, and 30 pesos in transfer fees. Your net is 420 pesos for the round trip.
Complete three of those round trips a week and you make about 1,260 pesos on roughly 56,000 pesos of inventory. That is real money, but it is closer to a side income than a salary, and it assumes nothing goes wrong.
Here is the sobering part. If one buyer tricks you with a fake receipt and you release 1,000 USDT, you lose about 56,000 pesos. At 420 pesos per round trip, that single mistake wipes out the profit from more than 130 clean trades.
Before committing money, run your own figures through a P2P profit calculator using the real fees of the platform you plan to use, then test what happens to your margin if spreads shrink by half.
Working capital: the money that sits still
A P2P merchant needs inventory on both sides. You need crypto ready for buyers and pesos or dollars ready for sellers, which means part of your capital is always parked.
If most of your customers want to buy, your crypto runs out and your cash pile grows. You then have to rebalance, often through another platform, which adds more fees.
Keep inventory in an asset you understand. Holding stablecoins limits price swings. Holding volatile coins such as bitcoin adds a second business, speculation, that you may not have signed up for.
Payment-method risk is the real business risk
Crypto transfers are final. Many bank and card payments can be disputed or recalled. That mismatch is the root of most P2P chargeback fraud: a buyer pays, receives the crypto, then reverses the payment.
Fake proofs are the other big threat. GCash has warned users that scammers use AI apps to create fake payment receipts, and advised checking the in-app transaction history rather than trusting screenshots. Treat every screenshot as a claim, not as money.
Escrow helps with part of this. On non-custodial marketplaces such as Senpero, the seller’s crypto is locked in a smart contract during the trade and released when the seller confirms the payment arrived. That protects the buyer from a seller who vanishes, but the seller still has to verify the money is really there before confirming.
The scale of fraud is large. The FBI’s Internet Crime Complaint Center recorded about $11.4 billion in crypto-related losses in 2025, up 22% on 2024.
Reputation and limits
On most P2P platforms, your completed trades and feedback become your storefront. Early on you will have few reviews, so keep order limits small and accept only payment methods you can verify yourself.
Your bank and e-wallet accounts have limits too, and a steady stream of transfers from strangers can prompt questions from your provider. Read their terms before you scale, and keep records that show where each payment came from.
Tax matters too. In the US, the IRS treats crypto as property, so selling or swapping can trigger capital gains. In the Philippines, ask an accountant how the BIR treats trading income, and keep a spreadsheet of every trade either way.
A first-month checklist
- Write down every cost line and check each against the platform’s published fees.
- Start with an amount of capital you can afford to lose entirely.
- Accept only payment methods where you can confirm settled funds in your own app.
- Never release crypto based on a screenshot or a customer’s urgency.
- Reject third-party payments where the sender’s name does not match the buyer.
- Log every trade with date, amount, rate, fees and counterparty.
- Review results after 30 days and make a clear call on whether it is a business, a hobby or a lesson.