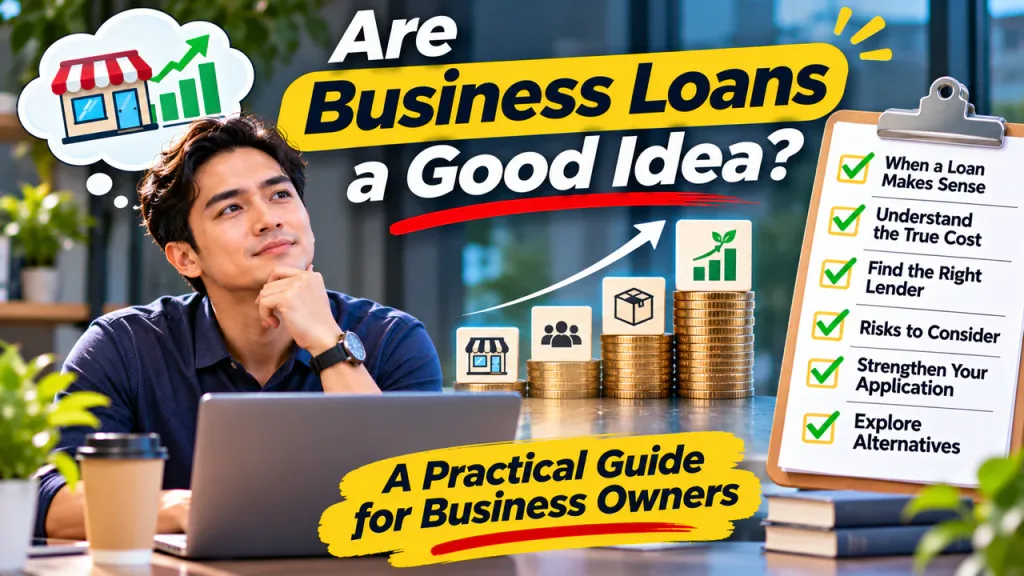
Starting or growing a business almost always brings a financial challenge to the surface at some point. Whether you need equipment, staff, inventory, or just a cash flow buffer to get through a rough stretch, the question of how to fund your next move is one every entrepreneur faces eventually. For many, a business loan enters the picture quickly as a potential solution. But is taking on debt actually the right call? The answer depends on several important factors worth thinking through carefully before you sign anything.
When a Business Loan Makes Sense
Not every financial need calls for a loan, but there are plenty of situations where borrowing makes clear strategic sense. If you have a defined growth opportunity in front of you, like a major contract, a new location, or a seasonal inventory push, a loan can bridge the gap between where you are and where you need to be. The key is having a solid plan for how those borrowed funds will generate a return that outpaces the cost of the loan itself. When the math works in your favor, a loan is not just acceptable.
Understanding the True Cost of Borrowing
One of the most important steps before taking out any loan is understanding exactly what it will cost you over time. Interest rates, origination fees, repayment terms, and prepayment penalties all factor into the total cost of borrowing, and they add up faster than most people expect. Many business owners make the mistake of focusing only on the monthly payment without calculating the full picture across the life of the loan. When comparing lenders and loan products, entrepreneurs who rely on business loan leads to connect with specialized financial partners can save a significant amount of money and stress by quickly identifying lenders best suited to their specific needs.
The Role of Business Loan Leads in Finding the Right Lender
Finding the right lender is just as important as deciding whether to borrow in the first place, yet many business owners overlook this step entirely. **Business loan leads** connect entrepreneurs with lenders and financial partners who specialize in funding businesses at various stages and across a wide range of industries. Rather than spending weeks cold-calling banks or submitting applications into the void, using a targeted lead service helps match your specific financing needs with lenders who are actually equipped to help you. This process saves valuable time and meaningfully improves your chances of landing favorable terms that fit your real situation.
Risks to Consider Before Taking the Plunge
Like any financial decision, taking out a business loan carries real risks that deserve honest consideration before moving forward. If revenue slows or an expected project falls through, loan repayments can quickly become a serious strain on your cash flow. Some loans also require personal guarantees, meaning your personal assets could be on the line if the business cannot repay the debt. Reviewing your financials carefully, having contingency plans ready, and avoiding the temptation to borrow more than your business can realistically support are all non-negotiable steps in this process.
How to Strengthen Your Loan Application
Lenders want to see that you are a reliable borrower with a clear, credible plan for using the funds you are requesting. Before applying, pull together your financial statements, tax returns, business plan, and any documentation that demonstrates consistent revenue or a strong growth trajectory. Your credit score, both personal and business, plays a significant role in determining what rates and terms you will qualify for. If your credit needs some work, taking a few months to clean it up before applying is often worth the wait, since even a modest improvement can translate to meaningfully better loan terms.
Alternatives to Traditional Business Loans
Business loans are not the only path forward when you need capital, and it is worth knowing what else is out there. Depending on your situation, you might explore business lines of credit, invoice financing, merchant cash advances, or even small business grants. Each option comes with its own set of benefits and trade-offs, so understanding the full landscape gives you more negotiating power and flexibility when the time comes. Comparing all available tools before committing to a loan ensures you are choosing the funding structure that genuinely fits your business model rather than just the first option that crosses your desk.
Conclusion
Business loans can absolutely be a good idea when approached strategically and responsibly. They give entrepreneurs the capital needed to seize opportunities, manage growth, and keep operations running smoothly through challenging periods. The real key is coming to the decision with clarity, doing thorough homework on costs and risks, and choosing a lender who is a genuine fit for your needs. With the right preparation and mindset, a business loan can be one of the most powerful tools in your financial arsenal.