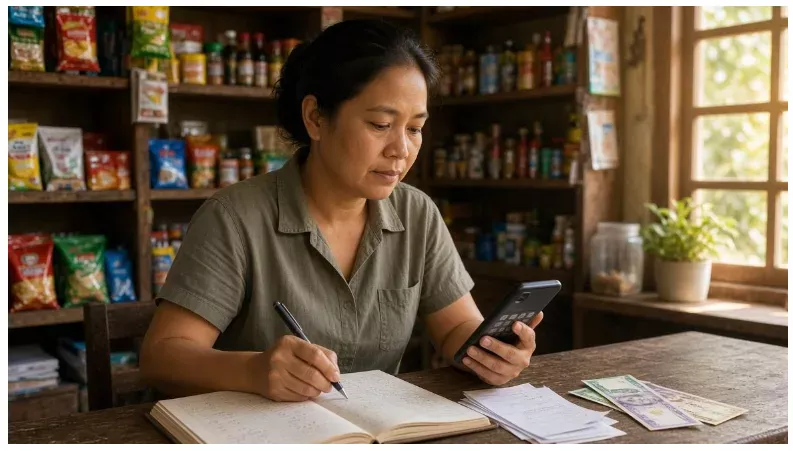
Ask any sari-sari store owner, freelance designer or restaurant operator in the Philippines what keeps them up at night. Many will not say “profit.” They will say “cash.” A business can look healthy on paper and still be unable to pay suppliers on Friday because a client’s payment has not arrived.
This gap between money earned and money in hand is the cash flow problem. It is the most common reason small businesses struggle, and it has little to do with whether the product is any good. Here is how to see it coming, shrink it, and borrow sensibly when you have to.
Profit and cash are not the same thing
Say you invoice a corporate client PHP 80,000 for a catering job. On your books, that is revenue. But the client’s accounting department pays on 45 day terms, while you bought ingredients, paid helpers and covered transport this week. For the next month and a half, you are out of pocket.
Profit measures whether the business model works. Cash flow measures whether you can keep operating while it works. Owners who track only sales often discover the problem when it is already urgent.
Step 1: Build a simple 13 week cash forecast
You do not need accounting software. A spreadsheet with weeks across the top and three rows is enough: cash coming in, cash going out, and the balance at the end of the week.
Fill in what you actually expect. Mark invoices on the date you realistically expect payment, not the due date. List fixed costs such as rent, payroll, SSS, PhilHealth and Pag-IBIG contributions, and utilities. Add the known spikes: taxes, license renewals, and the stock you must buy before December.
Within an hour you will see the weeks where the balance goes negative. A gap you know about three months ahead is a planning problem. The same gap discovered on the day is an emergency.
Step 2: Shrink the gap before you borrow
Borrowing should be the last lever, not the first. Several cheaper ones come before it.
Invoice faster and chase earlier. Send invoices the day the work is done. A polite reminder a few days before the due date works better than an angry message a month after it.
Offer a small incentive for early payment or a deposit. Asking for 30 to 50 percent upfront on larger jobs is normal in many industries and moves cash to your side of the timeline.
Negotiate with suppliers. A supplier who knows you pay reliably will often extend terms from 15 to 30 days. That alone can close a gap.
Reduce stock sitting on shelves. Inventory is cash you have already spent. Slow-moving items tie up money that could pay a bill.
Separate personal and business money. A surprising number of cash crunches come from owners drawing more than the business earns. A fixed owner’s pay, even a modest one, keeps the numbers honest.
Step 3: Know your borrowing options
If the forecast shows a gap you cannot close, borrowing can be reasonable, as long as the loan is short, the cost is clear, and the repayment date falls after the cash you are waiting on arrives.
The main options in the Philippines include:
- Bank or cooperative loans. Usually the cheapest, but approval takes time and often requires collateral or business records. Start these conversations before you need the money.
- Government-backed programs for micro and small enterprises. These exist through agencies that support small business financing. Terms and eligibility change, so check the current details directly with the agency.
- Lending and financing companies. Faster and more flexible, but usually more expensive.
- Online lending apps. The fastest option and the one that needs the most caution.
Step 4: Be careful with online lending apps
Online loan apps have made small, quick credit available to people who were once ignored by banks. They have also produced plenty of complaints about hidden fees, aggressive collection and misuse of personal data.
Before you install any app or submit an ID, check a few things:
- Is the company registered? Lending and financing companies operate under SEC authority, and the SEC publishes lists of registered companies and platforms. If the lender is not on the list, walk away.
- What is the real cost? Look at the total you will repay, not the headline rate. Processing fees deducted upfront mean you receive less than the amount you borrowed while still repaying the full amount.
- What permissions does the app request? A loan app has no business reading your contacts or photos. Excessive permissions are a warning sign.
- What do real borrowers say? Search the lender’s name together with the words “complaint” or “review.” Patterns repeat.
If you want a starting point for the checks above, our guide to legit loan apps in the Philippines explains how to verify a lender’s registration and compares lenders on their disclosed terms. Whatever source you use, confirm the details with the lender and the regulator before signing anything.
Step 5: Match the loan to the problem
A common mistake is using short-term credit to solve a long-term problem. If a PHP 20,000 loan due in 30 days pays for a gap that closes in two weeks, it can work. If it pays for a business that loses money every month, it only delays the problem and adds interest.
A simple test: write down exactly where the repayment will come from. If you can name the invoice, the sale or the season, the loan has a purpose. If the honest answer is “I will figure it out,” do not borrow yet.
Also be careful about borrowing from one lender to repay another. That cycle is how a manageable gap becomes a debt spiral.
Step 6: Build a buffer for next time
The best protection against the next gap is a small reserve. Many advisers suggest aiming for one to three months of fixed costs, built slowly. Even setting aside a small percentage of every payment received, as automatically as you can, makes the next crunch smaller.
Keep that reserve in a separate account so it does not get absorbed into daily spending.
The takeaway
Cash flow trouble is not a sign of a bad business. It is a normal feature of growing one. The owners who handle it well do three things: they forecast, they close gaps with timing and negotiation before they borrow, and when they do borrow, they choose regulated lenders, read the full cost, and make sure the repayment has a source.
Treat cash as the most important number in the business, check it weekly, and the surprises get a lot smaller.
This article is for general information and is not financial or legal advice. Loan terms and regulations change, so verify current details with the lender and the relevant agency before borrowing.